
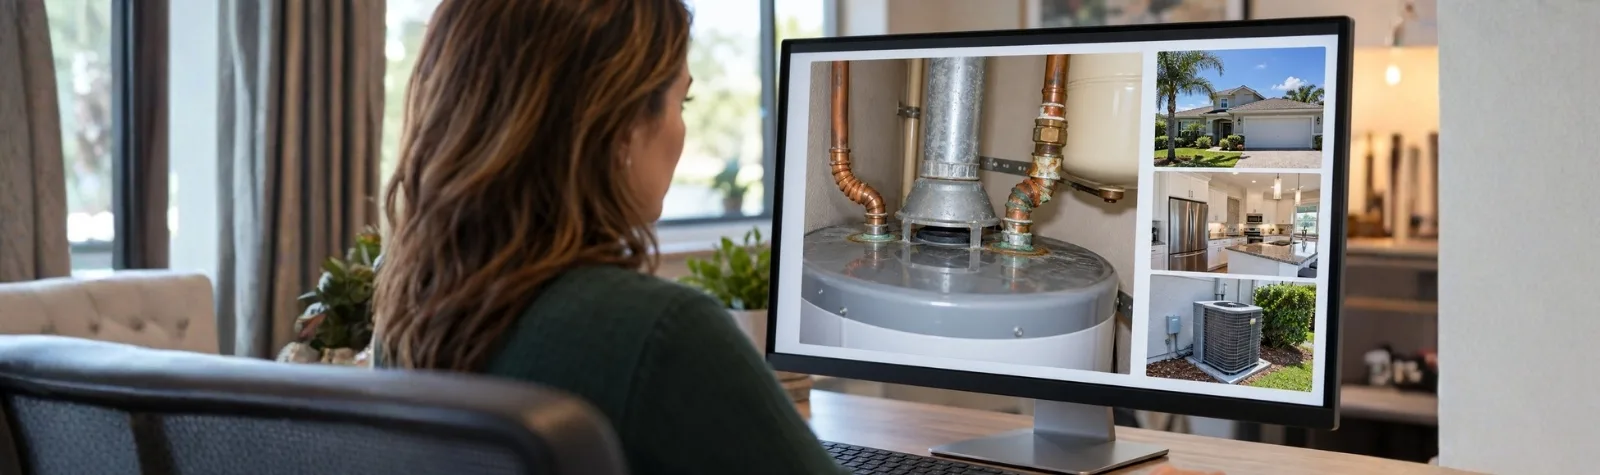
The short version: Guided photo surveys give insurers a current look at eligible homes. Image analysis can help flag conditions for review, while underwriters decide whether they need another photo, documentation, or an on-site inspection. As images become easier to alter or generate, how they are captured and checked becomes more important.
A renewal survey might show a renovated kitchen but a corroded supply line. The kitchen could prompt a review of replacement-cost information, while the supply line prompts questions about repairs. The value of the survey is that it gives the underwriter something specific to follow up on while the property is under review.
Why is the role of self-inspections growing?
Insurers need current information about properties they cover. Records and aerial images are useful, but they may miss recent interior work or the condition of a home system. A guided survey can bring those views into the underwriting file without arranging a visit to every eligible property.
When a homeowner is asked for particular views, the carrier receives a more consistent set of images to review. If an important view is missing, the carrier can request it. If a visible condition needs closer examination, an inspector can be sent to address that question.
This gives carriers more ways to match the review to the property. A photo survey may be enough to resolve a routine question. Another home may need a repair record, a separate report, or an on-site inspection.
How does AI change the review?
Some carrier programs use image analysis to flag possible hazards in homeowner-submitted photos. That can help reviewers find the images that need attention, particularly when a survey contains many views. It does not tell the whole story of the property. An underwriter still has to consider what the image shows, what other information is in the file, and what follow-up is appropriate.
The practical advance is a more focused review. A possible issue can be examined while the rest of the survey provides a current record of the home. For an agent, that may mean a request for a clearer image, an invoice showing when work was completed, or help arranging an inspection.
How can insurers rely on submitted images?
This question becomes more pressing as realistic images get easier to edit or generate. A clear photograph is useful only if the carrier can have reasonable confidence that it shows the insured property in its present condition.
Depending on the survey system, carriers can ask homeowners to capture images within a guided process, retain the original files and capture details, and compare submissions with other property information. An inconsistent or incomplete set of images calls for follow-up. Image checks help the underwriter assess the evidence; they cannot reveal a condition the homeowner did not photograph.
Will self-inspections replace on-site inspections?
For some eligible homes, a guided survey may answer the carrier’s questions. Other properties will still need an inspector’s judgment or a separate report. Self-inspections are likely to change when and why a field visit is ordered: the carrier can review current images first, then use a visit to resolve questions the images cannot settle.
Agents can help by making sure clients understand the views and deadlines in a carrier’s request. Clear, complete submissions reduce avoidable follow-up; Jerger’s guide to property photos explains what makes an image useful to an underwriter.
Inspection requirements depend on the carrier and the property. For questions about working with Jerger MGA or American Traditions Insurance coverage, contact our team.
